The Asymmetric Power of Principal Prepayment
Due to the mechanics of reducing-balance amortization, early loan installments consist primarily of interest charges. Conversely, any additional cash paid over and above your scheduled monthly EMI goes 100% directly toward reducing your principal balance.
This creates an asymmetric benefit: by eliminating principal early, you eliminate all the future interest that would have compounded on that principal for the rest of the loan term.
Case Study: The "13th Payment" Strategy
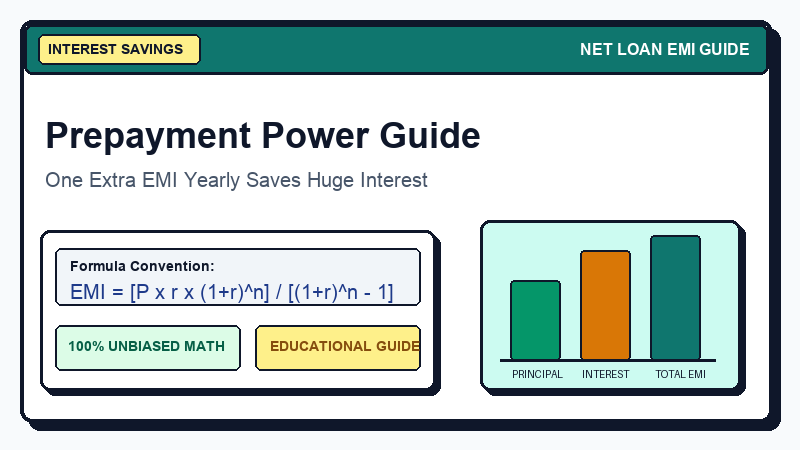
One of the most effective personal finance strategies is making the equivalent of one extra monthly EMI payment each calendar year. Let us examine the results on a typical $300,000 home loan at 6.5% interest over 30 years:
| Repayment Strategy | Monthly Outflow | Effective Loan Tenure | Total Interest Paid | Total Interest Saved |
|---|---|---|---|---|
| Standard 30-Year Schedule | $1,896.20 | 30 Years (360 Mos) | $382,633 | $0 (Baseline) |
| 1 Extra EMI Per Year ($158/mo extra) | $2,054.22 | 24.5 Years (294 Mos) | $302,410 | $80,223 Saved! |
| $300 Extra Per Month | $2,196.20 | 21.8 Years (262 Mos) | $263,892 | $118,741 Saved! |
Key Takeaway:
By contributing just $158 extra each month toward your principal, you shorten your loan term by 5.5 years and keep over $80,000 in your pocket rather than transferring it to the bank!
Two Ways Lenders Process Prepayments
When you make a lump-sum prepayment, lenders typically offer two options:
- Reduce Loan Tenure (Recommended): Keep your monthly payment identical and let the maturity date move closer. This maximizes interest savings.
- Reduce Monthly EMI: Keep the original maturity date and lower your monthly installment. This option provides immediate monthly cash-flow relief, but delivers smaller total interest savings than tenure reduction.
Important Rules to Verify Before Prepaying
- Zero Foreclosure Penalties: Ensure your loan agreement does not levy prepayment penalties. In many jurisdictions, floating-rate consumer loans are legally exempt from prepayment charges.
- Explicit Principal Tagging: Instruct your lender in writing or via their digital portal that your extra payment must be applied directly to Principal Reduction rather than held as advance interest for future months.
Test your numbers with our dedicated Home Loan EMI Calculator to model the impact of accelerated repayments.