The Core Borrowing Dilemma: Monthly Relief vs. Lifetime Cost
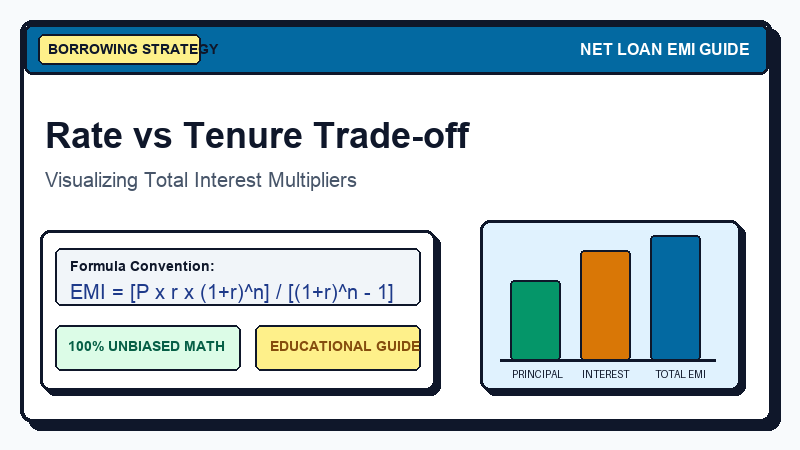
When selecting a loan, borrowers are naturally drawn to lower monthly installments. Lower installments leave more breathing room in the monthly household budget. However, lowering your monthly EMI by extending your loan tenure carries a massive, frequently underestimated penalty: a dramatic escalation in total interest paid over the life of the loan.
In this analysis, we examine the quantitative dynamics of how interest rates and loan durations interact, helping you pinpoint the optimal balance between cash-flow comfort and long-term wealth preservation.
The Tenure Multiplier: A $200,000 Mortgage Case Study
Consider a borrower taking a $200,000 home loan at a fixed interest rate of 7.0% per annum. Let us compare the results across four different loan durations:
| Loan Tenure | Monthly EMI | Monthly Savings vs 15-Yr | Total Interest Paid | Total Repayment Amount |
|---|---|---|---|---|
| 15 Years | $1,797.66 | Baseline | $123,578 | $323,578 |
| 20 Years | $1,550.60 | Save $247/mo | $172,144 | $372,144 |
| 25 Years | $1,413.56 | Save $384/mo | $224,068 | $424,068 |
| 30 Years | $1,330.60 | Save $467/mo | $279,017 | $479,017 |
Critical Financial Insights from the Data:
- The Diminishing Relief Effect: Increasing tenure from 15 to 20 years reduces your monthly payment by $247. But stretching from 25 to 30 years only reduces your monthly payment by $83! You gain minimal monthly relief in exchange for 5 extra years of compounding debt.
- The Interest Doubling Trap: Over 30 years, you pay $279,017 in interest alone—more than the original $200,000 borrowed! Compared to a 15-year tenure, the 30-year loan costs an astonishing $155,439 extra in pure interest.
The Compounding Impact of Interest Rate Hikes
Small movements in interest rates have magnified impacts as loan tenure lengthens. Consider the same $200,000 loan over 30 years at different interest rate brackets:
- At 6.0% p.a.: Monthly EMI is $1,199.10; Total Interest is $231,677.
- At 7.5% p.a.: Monthly EMI is $1,398.43; Total Interest is $303,434.
- At 9.0% p.a.: Monthly EMI is $1,609.25; Total Interest is $379,328.
A seemingly modest 3% increase in interest rate nearly doubles the total interest paid from $231,677 to $379,328!
Strategic Recommendations for Borrowers
- Choose the Shortest Affordable Tenure: Do not choose a 30-year loan simply because the lender allows it. If your income supports the 20-year or 15-year payment without violating the 35% debt-to-income threshold, opt for the shorter term.
- The "Hybrid" Strategy: If you are concerned about cash-flow flexibility, take the longer 30-year tenure to keep the mandatory minimum payment low, but voluntarily make prepayments each quarter as if you had a 20-year loan. This gives you downside safety during emergencies while maintaining accelerated interest reduction.
Experiment with different tenure and rate combinations on our Home Loan EMI Calculator to model your optimal repayment strategy.